Proptech Briefing
1) Key Takeaways
AI consolidation steps up: AECOM buying Consigli and Procore acquiring Datagrid show major incumbents are now acquiring, not just partnering with, AI‑native construction platforms. So what? Startups that genuinely sit in the design, planning or delivery “brain” of projects are now firmly on the strategic M&A menu, which should shape how founders think about ecosystem fit and exits.
Proptech‑adjacent AI and cybersecurity are hot: Elyos AI and Cyb3r Operations both raised significant rounds backed by Pi Labs to automate trades workflows and secure third‑party cyber risk respectively. So what? The stack around real‑estate operations is filling in - field‑service automation and cyber are quickly becoming table‑stakes expectations for serious platforms.
Housing pipeline data confirms supply pain: residential approvals in Q3 2025 fell to 45,075 units - the lowest quarter since 2012 - and Great Britain is 25% down on permissions for the first nine months of 2025 vs the prior year. So what? With delivery and planning clearly constrained, the most valuable proptech plays are those that help get more viable units through planning, funding and construction, not just those that market existing stock.
Institutional capital is moving more into specialist property credit, with CrowdProperty Australia securing two funding lines - an up‑to‑A$150m facility and an alliance with Aura Real Estate Credit, while JP Morgan’s Specialist Finance conversations highlighted growing appetite for data‑rich, asset‑backed lending platforms. So what? Lenders and originators who invest in underwriting, monitoring and reporting tech are best placed to tap these deeper pools of capital at attractive terms.
JLL Spark’s 2026 forecasts point to a shift from pilots to production, with 88% of firms piloting AI but only about 5% achieving their goals, and a likely uptick in IPOs and strategic M&A for platforms with strong data and workflow moats. So what? The “AI hype” phase is over; buyers now expect demonstrable ROI, integrated platforms and a clear path to profitability.
2) VC/PE Investment Activity
Orbital (real‑estate legal AI) raises $60m Series B to build a single, secure workspace for property law. So what? Real‑estate transactions are still document‑heavy and slow; this kind of vertical AI in legal workflows is key infrastructure for faster, safer deals across commercial and residential. proptechconnect.com
Elyos AI closes a $13m Series A (around £9.7m) led by Blackbird, with Y Combinator, Pi Labs and others backing AI “agents for the trades” that handle inbound requests, scheduling and comms for contractors. So what? Repairs and maintenance are where many landlord and operator P&Ls leak value - AI that makes field services faster, cheaper and more reliable will rapidly become part of the standard proptech toolkit. thesaasnews.com · fmj.co.uk
Cyb3r Operations raises a £4m seed round to fix the third‑party cyber blindspot, led by Octopus Ventures with participation from Pi Labs and others. So what? As real‑estate owners layer on more SaaS and data integrations, cyber risk becomes an existential operational concern; expect investors and customers to scrutinise security posture as closely as product roadmap. pulse2.com
Pi Labs opens applications for its 2026 Growth Programme, targeting earlier‑stage proptechs with product‑market fit that now need help scaling revenue, partnerships and international expansion. So what? In a selective funding environment, structured programmes that combine capital, customer access and scaling support can materially accelerate the best mid‑stage platforms. pilabs.vc
Proptech funding rebounded to $16.7bn in 2025, up 68% year‑on‑year, with capital concentrating in AI, ops platforms and structured financings. So what? Despite macro jitters, serious capital is flowing back into the category - founders with strong unit economics and real‑asset exposure are firmly back in favour. multifamilydive.com
3) Market Insights
Global proptech market size is estimated at around $53–55bn in 2026, with forecasts to $120–185bn by 2031–34 at mid‑teens CAGRs, led by cloud solutions and commercial/industrial adoption. So what? This underlines that proptech is now a large, fast‑growing software category in its own right, not a niche - helpful context for boards and LPs allocating capital to the space. globenewswire.com
The HBF Housing Pipeline Q3 2025 report shows just 45,075 units approved - the lowest quarter since Q2 2012 - with approvals for 2025 Q1–Q3 down 25% year‑on‑year to 146,798 units, including falls of 39% in the North, 21% in the Midlands and 13% in Southern England. So what? The supply crunch is national: proptech that helps identify viable land, assemble evidence and get schemes through planning is operating against a structurally shrinking pipeline, not just a London issue. hbf.co.uk
Glenigan’s Construction Review reports housing detailed approvals down 38%, starts down 3% and housing main contract awards down 19% in 2025, while industrial and office project starts rose 31% and 32% respectively. So what? Resi is struggling to get out of the ground, but logistics, manufacturing and data‑centre projects are surging - proptech founders should be honest about which asset classes actually have capex momentum. glenigan.com
CrowdProperty’s January 2026 State of the Market notes flat house prices, subdued but steady transactions and persistent planning delays, but an improving outlook as rates ease and mortgage approvals slowly trend up. So what? 2026 looks like a year for disciplined, data‑driven growth rather than swinging for the fences - particularly for lenders backing SME developers. crowdproperty.com
4) Chart of the Month
London Permanent Dwelling Starts (12-month rolling) - “falling off a cliff”
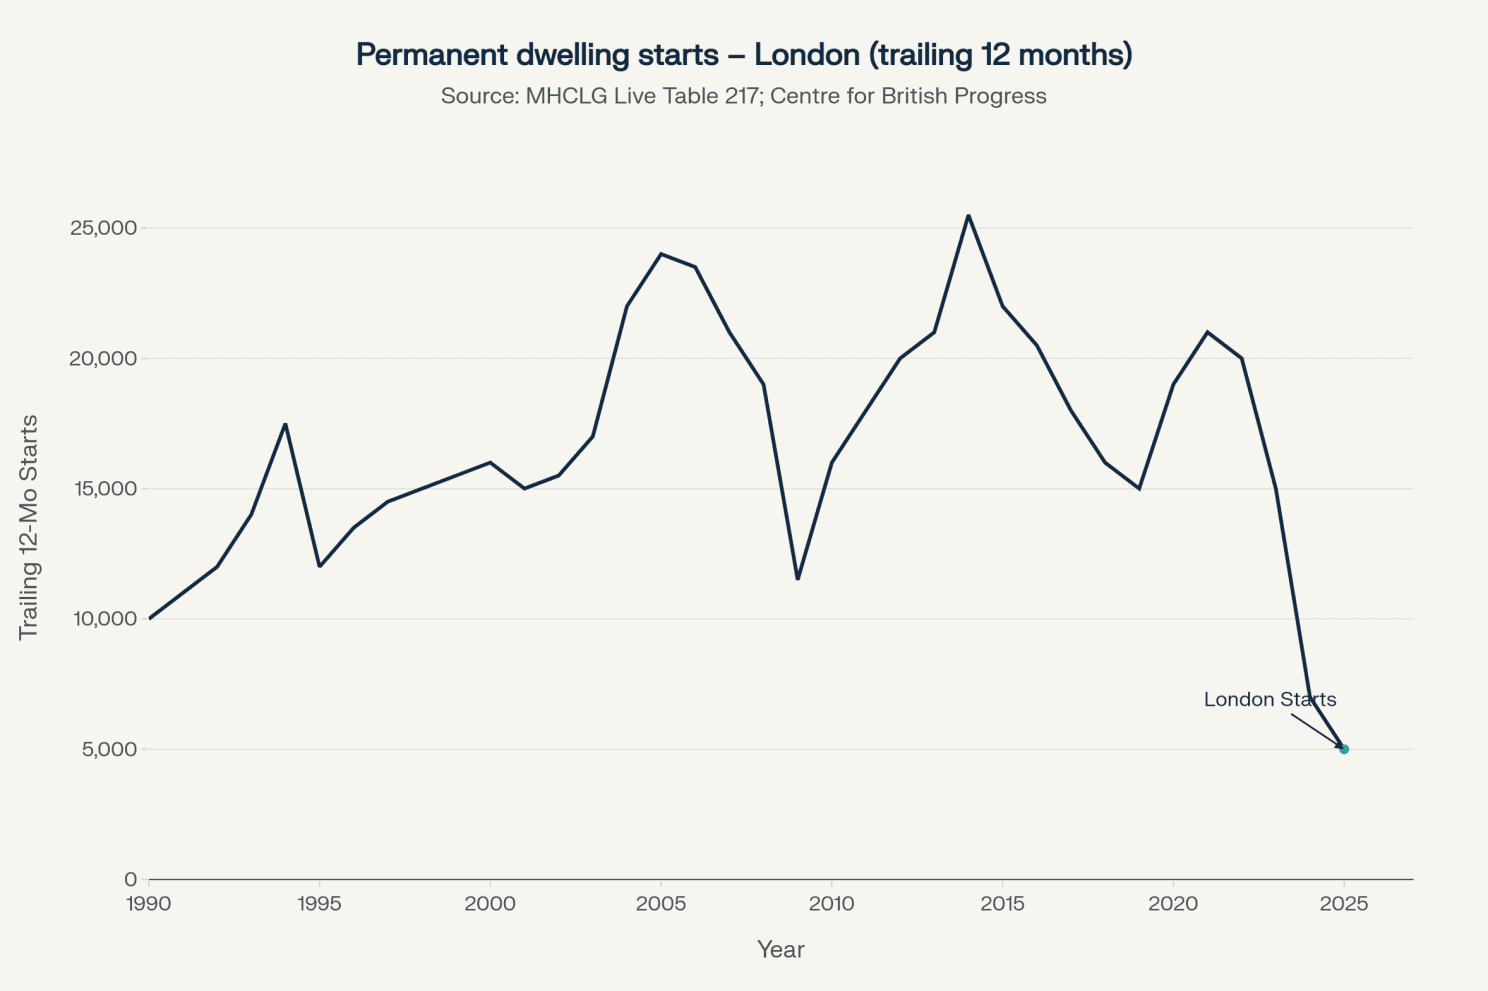
Permanent dwelling starts (trailing 12 months) in London have plunged from peaks above 20,000 in the mid‑2010s to around 5,000 - charting the steepest drop in the series since the early 1990s.
So what? This visual makes the supply crisis tangible: even if demand wobbles, the bigger long‑term opportunity is in technology that can help deliver more homes - via better planning, design, construction and funding - rather than betting on short‑term price moves.
5) Number of the Month
20% - the YoY decline in UK construction project starts (2025 vs 2024) in Glenigan’s January 2026 review.
So what? This is the “real economy” constraint behind delayed delivery, contractor capacity stress, and more conservative lender/investor behaviour. Every home not built takes well over £100,000 of spend on labour, materials and services out of the economy and makes the UK Government’s 1.5m housebuilding target in this parliamentary term ever more unlikely.
6) Operator Play of the Month
Housekeep: move from “cleaning marketplace” to “national home services platform”. Housekeep’s January update positions the business for a 12-month push to make all core services available nationwide (cleaning, gardening, handymen, electricians, appliance repair, etc.), using plumbing/drain unblocking as the latest expansion wedge. housekeep.com
So what? Whoever owns the highest‑frequency, tech‑enabled relationship in the home will be best placed to bolt on insurance, energy and landlord products at scale.
7) Policy & Regulation Radar
MHCLG Digital’s work on faster, clearer local plan-making guidance and timelines continues to point to a more standardised, process-driven regime. So what? This should be tailwind for plan-tech, digital planning pipelines, and structured data ingestion. mhclgdigital.blog.gov.uk
8) Deep Dives on Hot Topics
Proptech × Fintech Intersect
JP Morgan’s Specialist Finance Conference emphasised growing institutional appetite for asset‑backed lenders that can provide granular, real‑time data across origination, risk and collections. So what? Tech‑light lenders will struggle to compete on cost of capital; the winners will be platforms that treat data architecture and governance as core product, not back‑office admin. Read my take from the conference here: linkedin.com
Real‑estate tokenisation is preparing for a “serious” 2026, with Dubai’s Land Department’s tokenisation initiatives and European platforms such as BrickMark/Tokeny surpassing €200m in tokenised deals. So what? Tokenisation is shifting from experiments to regulated, state‑linked infrastructure - important for anyone working on secondary markets, fractionalisation or RWA‑backed credit. blog.tokenizer.estate
CrowdProperty Australia aligns with Aura Real Estate Credit, pairing a tech‑enabled origination and servicing platform with institutional capital to fund Australian residential development. So what? This is the platform‑plus‑capital model playing out in another market - institutions increasingly prefer to plug into specialist, data‑rich originators rather than build their own granular deal‑sourcing machines. crowdproperty.com.au
CrowdProperty Australia also secured an up‑to‑A$150m funding facility to support SME developers, with loan applications reportedly running at around A$100m per month as planning reforms and demand unlock more smallprojects. · So what? Once platforms prove underwriting discipline and servicing quality, institutional lines can scale quickly - further evidence that specialist fintech/proptech lenders are a durable part of the capital stack. crowdproperty.com.au
AI in Real Estate
AECOM’s acquisition of Consigli brings an “autonomous engineer” into a global firm - using AI to compare design options, generate MEP calculations, optimise building fabric and produce engineering reports up to 90% faster. So what? This is a clear sign that AI‑based design and pre‑construction tools are now board‑level strategic assets; expect more large consultants and contractors to buy rather than build similar capabilities. aecmag.com · jdsupra.com
Procore’s acquisition of Datagrid adds deep AI search and agentic workflows across construction data - automating repetitive tasks like submittal review, RFIs and cross‑system information retrieval from drawings, emails and models. So what? Construction data platforms are rapidly becoming AI‑first; niche tools that don’t integrate with these ecosystems or add unique intelligence risk being squeezed out. engineering.com · uk.investing.com
JLL Spark’s 2026 forecasts describe a “critical shift from pilots to production”, with 88% of firms piloting AI but only about 5% achieving their goals, and a move from fragmented point solutions to integrated platforms that connect deal sourcing, underwriting, asset management and investorreporting. · So what? To win enterprise budgets, proptech vendors need to plug into core data infrastructure and demonstrate measurable NOI, risk or capex benefits - not just offer a clever point feature. spark.jllt.com
9) Events
PropTech Connect Middle East, Dubai, 4–5 Feb 2026 - proptechconnect.com
London PropTech Show, London, 24–25 Mar 2026 - proptechshow.com
UKREiiF, Leeds, 19-21 May 2026 - ukreiif.com
PropTech Connect Europe, London, 9-10 Sep 2026 - proptechconnect.com
UK Events Programme: UK PropTech Association (UKPA) Events - ukproptech.com
US Events Programme: PropTechVision Events calendar - proptechvision.com
10) Further Reading
2026 industry forecasts from the JLL Spark team. So what? A rare, candid view from a major strategic investor on how AI, data infrastructure and platform consolidation will reshape CRE and proptech this year. spark.jllt.com
CRETI / Multifamily Dive 2025 Proptech Funding Summary. So what? Good for framing where capital actually went in 2025 (AI, ops, structured financings) and that overall dollars are up vs 2024. multifamilydive.com
Recent proptech market‑size reports (Precedence / Mordor / Fortune). So what? Gives readers a credible sense of category scale and where growth is concentrated (commercial/industrial, Asia‑Pacific, cloud deployment). fortunebusinessinsights.com / mordorintelligence.com
State of the Market – January 2026 (CrowdProperty). So what? A concise, data‑rich summary of UK housing, lending and development dynamics - useful context for anyone operating at the intersection of proptech and specialist finance. crowdproperty.com
Housing Pipeline – Q3 2025 (Home Builders Federation / Glenigan). So what? The definitive dataset on UK residential planning approvals, underpinning the “supply crunch” thesis and highlighting where regional opportunities still exist. hbf.co.uk (data as summarised in the attached report)
UK PropTech Awards 2025 - full winners list. So what? Fastest way to spot where UK buyers and judges think real value is being created - ukproptech.com
Pi Labs: Agentic Investor research - pilabs.vc
For UK residential property market insights, subscribe to the CrowdProperty UK Newsletter - linkedin.com
For Australian residential property market insights, subscribe to the CrowdProperty Australia Newsletter - linkedin.com
Mike Bristow
Founder of Growth Strategy. Operator, advisor and investor across strategy, capital, M&A and board roles.
About Mike
More perspectives
Strategy & Growth
Make sharper choices, build sustainable advantage and turn strategic intent into measurable enterprise value.
Capital
Secure and optimise the institutional capital required to lend, invest, acquire, build or scale.
M&A & Transactions
Prepare, position and execute acquisitions, disposals, liquidity events and strategic partnerships.
Board & Executive
Add experienced judgement, challenge and execution capacity at board and executive level.